Hyperliquid Founder Draws Line Between Network and Trading Firms in U.S. Oversight Debate
Hyperliquid founder Jeff Yan said U.S. oversight should focus on firms using the blockchain rather than the underlying network itself, highlighting a central question in crypto regulation.
By Chloe ·
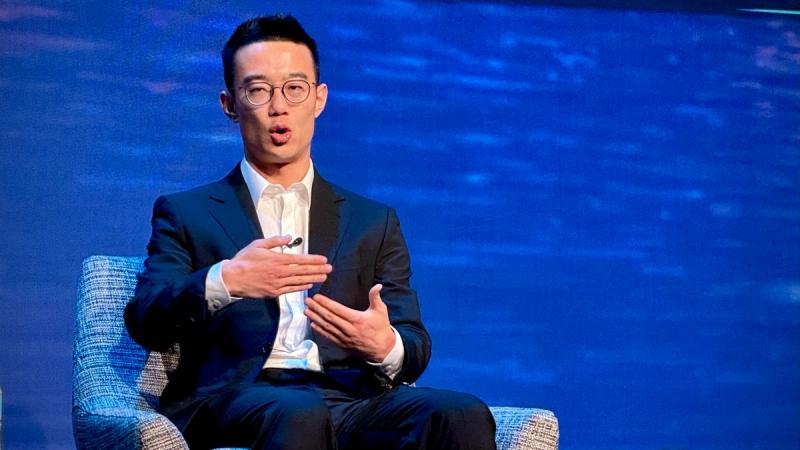
Hyperliquid founder Jeff Yan has argued that U.S. regulatory oversight should be directed at the firms operating through the network, rather than at the underlying blockchain itself. His position separates the technology that records or supports activity from the businesses that use it to provide trading services.
A question of where oversight belongs
The distinction is central to how regulators and the crypto industry define responsibility. Under Yan’s view, the blockchain would be treated as infrastructure, while companies using it would be the entities subject to oversight. That approach places the regulatory focus on identifiable firms and their activities instead of applying the same treatment to the network beneath them.
For the digital-asset market, the issue is more than a debate over terminology. It concerns whether rules should attach to the technology itself, to the organizations building services on top of it, or to both. The answer can affect how decentralized networks and trading platforms are evaluated, even when they are closely connected in practice.
Why the distinction matters for Hyperliquid
Hyperliquid’s founder made the comments in an interview with Bloomberg. The remarks put the project’s underlying blockchain and the firms using it into separate categories for regulatory purposes, rather than treating them as a single activity. That framing could inform broader discussions about how U.S. authorities approach blockchain-based trading infrastructure.
The comments do not, on their own, establish a change in U.S. policy or describe a specific regulatory action. They instead set out Yan’s preferred boundary: oversight should apply to the businesses conducting activity through a blockchain, while the network itself should not be the primary regulatory target. That distinction is likely to remain relevant as policymakers consider how existing oversight models fit crypto markets.
Source: Coindesk